Image Credit: Pexels
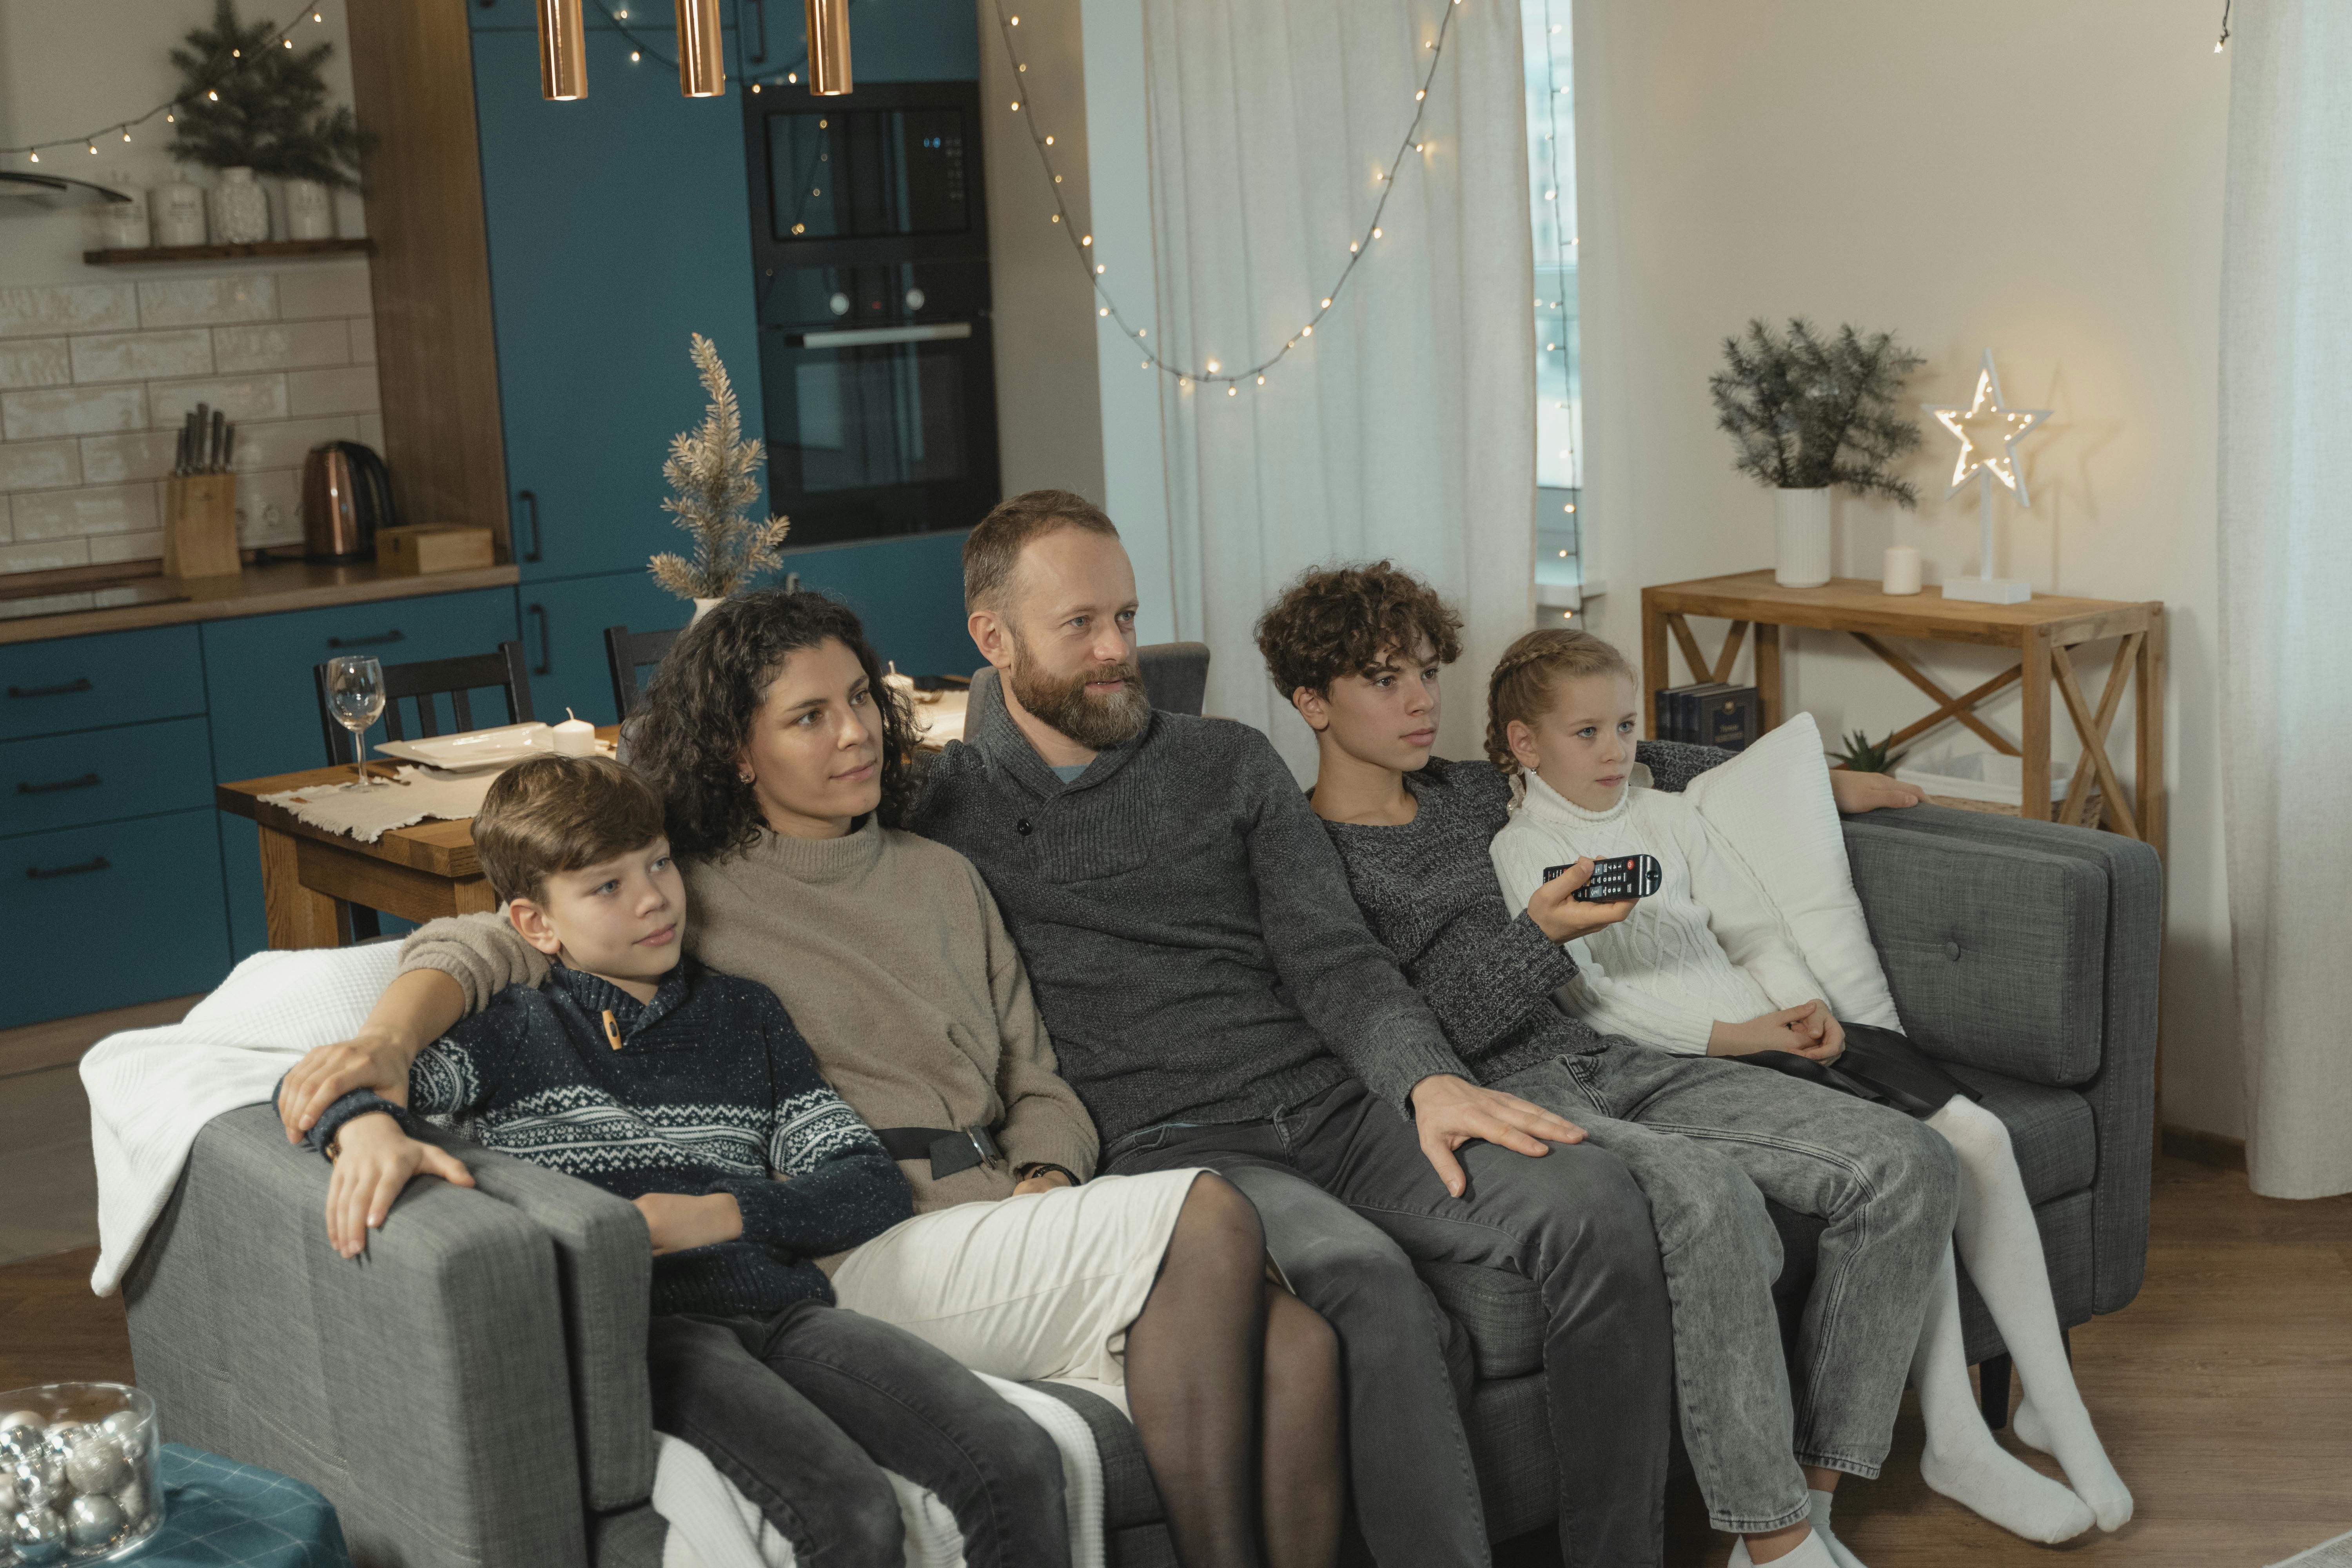
A bigger home can feel out of reach when bedrooms are already shared, toys fill every cupboard and property prices keep stretching the family budget. Yet buying a larger home doesn’t always require taking on a standard mortgage for the full purchase price. Affordable ownership schemes, resale opportunities and gradual buying options may offer another route. The key is to look beyond the headline price and calculate what your family can comfortably manage each month.
Outgrowing the Nursery Stage
The need for more room often becomes clear once a cot turns into a bed or a second child arrives. A two-bedroom home that once felt spacious can quickly lack quiet areas for sleep, homework and remote working.
Before searching, list the spaces that would genuinely improve family life. You might need one extra bedroom, better storage or a safe outdoor area, but not a huge kitchen or separate dining room. This keeps the search focused and protects your budget.
Once you know what your family needs from a larger home, check that your budget supports those priorities. These tips for first-time home buyers cover affordability, saving for a deposit and planning for the costs that continue after moving day.
A detailed affordability review helps too. Use a first-home affordability guide to account for upfront costs, monthly payments and the expenses that continue after moving day.
When Standard Mortgages Fall Short
A lender may offer less than you expected, particularly if childcare costs, loans or irregular income affect its calculations. That result doesn’t automatically end your plans. It shows how much breathing room your household finances need.
Start by reviewing three months of bank statements. Add up housing costs, food, transport, childcare, subscriptions and debt payments. Then test a larger housing payment for several months by moving the difference into savings. If your current payment is £1,100 and the expected new cost is £1,400, save the extra £300 each month.
Families who cannot comfortably afford a full open-market purchase may want to explore resale shared ownership properties. These are previously owned homes sold by existing shared owners, allowing eligible buyers to purchase at least the share currently held by the seller and pay rent on the remaining share. Before applying, compare the mortgage, rent, service charges and other household costs to check whether the arrangement fits your family’s budget.
Tapping into Secondary Affordable Schemes
Shared ownership resales are pre-owned homes where the current owner sells their share. You buy that available share and usually pay rent on the portion you don’t own. Since the home has already been lived in, you may also gain a clearer picture of running costs, room sizes and the local community.
Check every cost before applying. Ask about the service charge, rent, lease terms, repairs and any restrictions on future sales. Confirm how often charges can change and request recent statements where available.
Your affordability calculation should include council tax, insurance, commuting and maintenance. This bigger-home budget guide gives useful prompts for testing how a higher monthly payment may affect everyday spending.
Gradual Steps Toward Complete Ownership
Some shared owners can buy further shares in their home over time through a process commonly called staircasing. Each purchase may reduce the rent charged on the remaining share, though service charges and other housing costs can continue.
Treat future share purchases as a long-term possibility, not a guaranteed deadline. Salary changes, childcare bills and interest rates may all affect when another purchase becomes affordable. Set up a separate home fund and contribute a realistic amount after every payday, even if it’s modest.
Before increasing your share, request a full estimate covering valuation, legal and administrative fees. Compare that total with your emergency savings so the transaction doesn’t leave your family exposed to an unexpected boiler repair or income gap.
Creating a Long-Lasting Family Sanctuary
A larger property works best when it can adapt as children grow. Look for bedrooms that can fit full-size beds and desks, storage that keeps busy areas usable and a layout that offers some separation between noisy and quiet activities.
Spend time near any prospective home during the school run and in the early evening. Check travel times, nearby green spaces and access to childcare, schools and everyday shops. A cheaper home can become costly if it adds hours of commuting or requires a second car.
Give yourself room for normal family life in the final budget. The best move leaves enough money for repairs, clubs, birthdays and the occasional day out, while giving everyone a home that still fits several years fro
Let us know if you enjoyed this post!
Like
Love
Happy
Haha
Sad